November 2026 Client Profile

Marcus owns a mid-size HVAC installation company that had a strong 2026, generating $850,000 in adjusted gross income (AGI). As the year winds down, his advisor helps him plan a $40,000 charitable gift to a local trade-school scholarship fund.

Because 2026 introduces a new rule under the One Big Beautiful Bill Act, itemized charitable deductions only count above 0.5% of AGI. With Marcus’s AGI near $850,000, the first $4,250 of his giving produces no deduction, leaving $35,750 deductible. Rather than writing a check, his advisor suggests donating appreciated stock from his brokerage account instead. By gifting shares he’s held for years, he avoids capital gains tax on the appreciation while still deducting the full fair market value above the floor. Because Marcus is in the top tax bracket, OBBBA also caps his itemized deductions at 35%, slightly below his 37% marginal rate. Even so, pairing the gift with appreciated stock meaningfully reduces his 2026 tax bill and supports a cause he cares about — proof that timing and asset choice both matter.

Client Profile is based on a hypothetical situation. The solutions discussed may or may not be appropriate for you.
Lower Your Tax Bill for 2027

Thanks to the One Big Beautiful Bill Act (OBBBA), 2027 planning can largely follow your 2026 tax plan, with a few adjustments and timely options.

WORTH YOUR SALT

Take full advantage of the higher state and local tax (SALT) deduction, up to $40,400 in 2026, through 2029, when it’s scheduled to return to $10,000. The cap phases down once your modified adjusted gross income (MAGI) exceeds $505,000 ($252,500 for married filing separately). At a MAGI of $612,730 or higher ($306,365 for married filing separately), the cap drops back to $10,000 in 2030.

OLD STANDBYS

Contribute the maximum allowed to tax-deferred employer retirement plans, IRAs, and Health Savings Accounts (HSAs). However, if you earned more than $150,000 in wages in 2026, your 2027 catch-up contributions to 401(k), 403(b), and governmental 457(b) plans must be made to a Roth account. HSAs remain among the most tax-efficient accounts available. Contributions are above-the-line deductions, growth is taxfree, and withdrawals for qualified medical expenses are also tax-free.

WHILE YOU CAN

Through 2028, you can deduct up to $10,000 in interest paid on a qualified car loan for a new vehicle assembled in the United States. You must purchase the vehicle between January 1, 2025, and December 31, 2028. The deduction phases out beginning at $100,000 MAGI for single filers and $200,000 for married filing jointly.

The 2028 expiration date also applies to the additional deduction of up to $6,000 per person age 65+. This deduction phases out at $75,000 MAGI for single filers and at $150,000 for married filing jointly.

BE AWARE

Charitable contributions are now deductible only to the extent they exceed 0.5% of your adjusted gross income (AGI). For example, a taxpayer with $300,000 in AGI receives no deduction for the first $1,500 of charitable giving. If you’re in the 37% tax bracket, you’ll receive only a 35% tax benefit from itemized deductions (including charitable contributions). You can no longer deduct miscellaneous investment fees, unreimbursed employee expenses, or personal tax preparation costs. Before implementing your 2027 tax plan, talk with your tax advisor.

Give Yourself Peace with a Tax Professional

Navigating the ever-changing tax landscape can be overwhelming, especially with complex rules and potential penalties. The One Big Beautiful Bill Act (OBBBA) affects all taxpayers and is accompanied by numerous existing inflation adjustments that influence everything from retirement and estate planning to personal and corporate income-tax brackets. Here are the main reasons to work with a tax professional.

  1. Expertise and Up-to-Date Knowledge: Tax laws constantly change. Professionals keep current through ongoing education, ensuring compliance and identifying opportunities you might overlook.
  2. Maximize Deductions and Credits: They identify lesser-known deductions, credits, and strategies to minimize your tax liability, often saving more than their fee.
  3. Save Valuable Time: Preparing taxes yourself can take hours or days. A professional handles it efficiently, freeing you to focus on what matters.
  4. Reduce Errors and Audit Risk: Mistakes trigger penalties or audits. Experts minimize errors and can represent you if issues arise.
  5. Peace of Mind and Year-Round Advice: Enjoy stress relief knowing it’s done correctly, along with proactive planning for long-term financial benefits.

A tax professional collaborates with you on a tax plan tailored to your specific situation. In 2026, amid ongoing regulatory changes, working with a tax professional remains an investment in accuracy and savings.

Can You Claim These Non-Itemized Deductions?

OBBBA also introduced several deductions for 2026 that you can claim in addition to the standard deduction without having to itemize your deductions.

Charitable Contributions. This permanent deduction lets you claim up to $2,000 (married filing jointly) or $1,000 (single) in cash qualified charitable deductions.

Student Loan Interest of up to $2,500 remains deductible in 2026, with a phase-out between $170,000 and $200,000 MAGI for joint filers and between $85,000 and $100,000 for single filers. However, starting with the 2026 tax year, forgiven student loan debt generally becomes taxable income again.

Vehicle Loan Interest of up to $10,000 a year can be deducted, effective for 2025 through 2028. You must purchase the vehicle for personal use and meet other eligibility criteria.

Additional Deduction for Seniors. If you’re age 65 or older, you’re eligible for an additional deduction of $6,000 (single) or $12,000 (married filing jointly). The deduction phases out for taxpayers with income over $75,000 (single) and $150,000 (married filing jointly).

Qualified Tips. For tax years 2025 through 2028, you can deduct up to $25,000 in tips received. To qualify, these tips must be received in occupations that customarily and regularly receive tips. The deduction phases out for single taxpayers with modified adjusted gross income (MAGI) over $150,000 and married couples (filing jointly) with income over $300,000.

What are “Trump Accounts”?

Introduced in the One Big Beautiful Bill Act (OBBBA), these are governmentfunded investment accounts designed to help children build wealth from birth. Children born between January 1, 2025, and December 31, 2028, who are U.S. citizens and have a Social Security number, are eligible to receive a one-time $1,000 deposit from the U.S. Treasury to start the account. Children born outside these four calendar years are also eligible for an account, but they won’t receive the $1,000 in government seed money.

MAKING CONTRIBUTIONS

Parents, grandparents, and other individuals can make after-tax contributions of up to $5,000 per year to each account. Employers may also contribute up to $2,500 a year to accounts for their employees’ dependents. Any employer contributions also count toward the overall $5,000 cap. The contributions grow tax-deferred until withdrawn. Account investment options are limited to mutual funds* or exchange-traded funds that track a qualified index, such as the S&P 500.

EDUCATION PLANNING

Beginning the year the child turns 18, they can make penalty-free withdrawals for qualified educational costs. The child will incur regular income tax on earnings and tax-free contributions from the government and employers. Still, all after-tax contributions made by parents and others can be withdrawn tax-free. After age 18, the account functions similarly to a Traditional IRA, with continued tax-free growth and the ability to withdraw funds for any purpose starting at age 59-1/2.

Opening an account makes sense if your child is eligible for the $1,000 seed money. It may also be worth considering if your employer is willing to contribute to your child’s account. Accounts can be opened beginning July 4, 2026. More guidance from the Treasury is expected before then.

*Investors should carefully consider the investment objectives, risks, charges, and expenses of the fund before investing. Contact the issuing firm to obtain a prospectus, which should be read carefully before investing or sending money. Because mutual fund values fluctuate, redeemed shares may be worth more or less than their original value. Past performance won’t guarantee future results. An investment in mutual funds may result in the loss of principal.

OBBBA and Alternative Minimum Tax

Initially designed to ensure that high income earners who benefit from various deductions and credits still pay a minimum level of tax, the Alternative Minimum Tax (AMT) is imposed at a flat rate tax of 26% or 28%. The 28% applies to taxpayers filing jointly with $244,500 or more AMT income (AMTI) and $122,500 or more for other taxpayers. You’ll be subject to AMT if your tax calculated under the AMT rules is higher than your tax calculated under regular income tax rules.

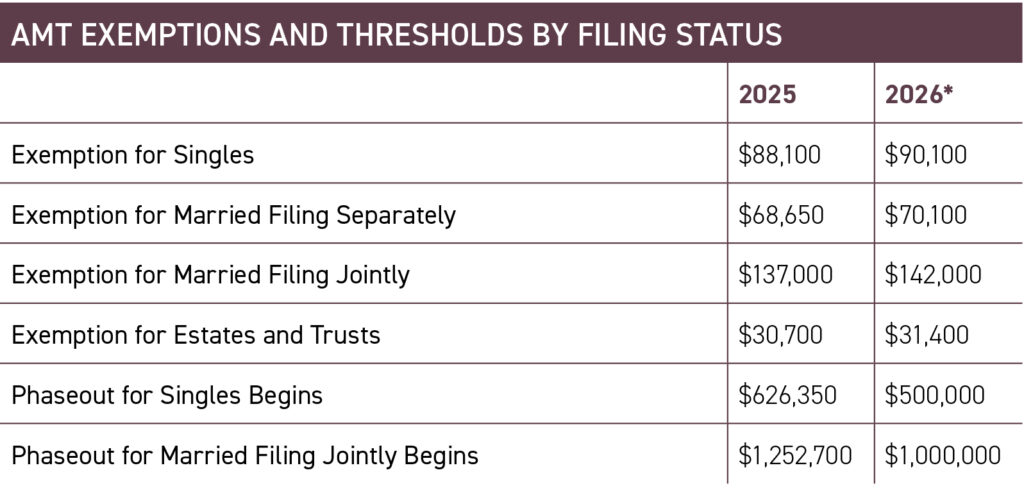
Before the Tax Cuts and Jobs Act (TCJA), AMT had increasingly affected a broader range of taxpayers due to its different rules and exemption structure. TCJA reduced AMT exposure, but those relief measures shift under the One Big Beautiful Bill Act (OBBBA) starting in 2026. As you see in the table below, for 2025, the phaseout of the exemption that single taxpayers may claim before AMT is imposed at $626,350 in AMTI. For married couples filing jointly, the phase begins at $1,252,700 AMTI.

Starting in 2026, however, OBBBA resets the exemption phase-out thresholds to the TCJA’s $500,000 and $1 million AMTI, with annual inflation adjustments for 2026 and beyond. So, for 2026, these phaseout thresholds will be lower than in 2025. More bad news: OBBBA also increases the exemption phase-out percentage from 25% to 50%. As a result, more high-income individuals may be hit with the AMT starting in 2026.

The AMT is complicated. Contact your tax professional to determine your status under the OBBBA changes.

*IRS Rev. Proc. 2025-32

The One Big Beautiful Bill Act (OBBBA)

As you look back on 2025 and start planning your financial strategies for 2026, here’s a brief overview of provisions in the OBBBA that you may want to consider in that planning.

PERSONAL TAXES

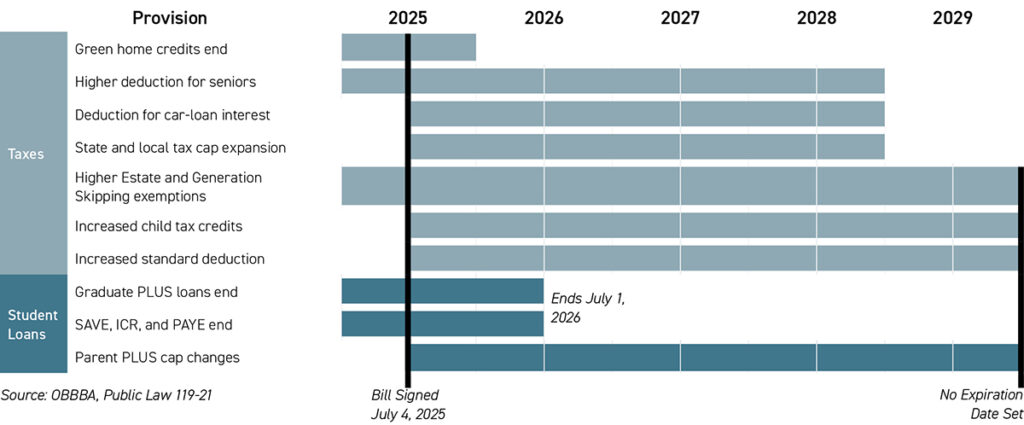
OBBBA retains the reduced federal income tax brackets introduced in 2017, which were scheduled to expire in 2026, and sets the 2026 standard deduction at $15,750 for single filers and $31,500 for married couples filing jointly, with inflation adjustments expected in subsequent years.

For 2025, the federal child tax credit increases to $2,200 per child. It will be indexed for inflation in 2026 and later. This credit begins phasing out for single/head of household taxpayers and married filing jointly at $200,000 and $400,000 modified adjusted gross income (MAGI). As for your estate planning, the estate tax exemption rises to $15 million for 2026 (from $13.99 million in 2025) and will be indexed for inflation in future years.

A new deduction for interest paid on auto loans could let you write off a portion of your car loan interest. The deduction has income limits and strict rules on which cars qualify. The cap on state and local tax (SALT) deductions is temporarily increased from $10,000 to $40,000 from 2025 through 2029, with the cap rising 1% annually until it reverts to the previous $10,000 limit in 2030. The expanded cap phases out for filers earning more than $500,000 (married filing jointly) or $250,000 (single).

FOR BUSINESSES

OBBBA makes permanent the 20% small business deduction for pass-through entities such as partnerships and sole proprietorships. It makes permanent the lower corporate tax structure and rates set to expire in 2025, as well as 100% bonus depreciation and full expensing for business investments.

For more specific information on how the Act may affect you, talk with your trusted tax and financial professionals.