Higher SALT Cap May Change Your Filing Status

New limits for 2026 could open the door to bigger tax savings.

HIGHER DEDUCTION LIMIT

The 2026 SALT cap is $40,400 – about 4x the old $10,000 limit.

MORE TAX SAVINGS

Combined with mortgage interest and charitable giving, you may now exceed the standard deduction by itemizing.

TIME-SENSITIVE

The higher cap phases down above $505,000 MAGI and reverts to $10,000 in 2030.

GET EXPERT ADVICE

Your tax professional can run both scenarios to see what saves you more.

Key Deadlines to Consider

Below are some key dates to consider as we approach the end of the year. By doing a little year-end planning now, you can optimize your unique financial situation.

Extended Tax Filing Deadline: October 15

The final extended date for individual taxpayers to file their federal income tax returns for the 2025 tax year if they filed Form 4868 by April 15, 2026.

Retirement Contributions & Conversions: December 31

Deadline to complete Roth IRA conversion and to take Required Minimum Distributions (RMDs) from Traditional IRAs and 401(k)s.

Charitable Contributions: December 31

The last day to make monetary or property donations that qualify for a federal income tax deduction on your 2026 tax return.

Capital Gains and Losses: December 31

The final day to sell non-qualified securities (stocks, bonds, mutual funds) to recognize a taxable gain or claim a loss for 2026.

October 2026 Question and Answer

QUESTION:

What is a SALT deduction?

ANSWER:

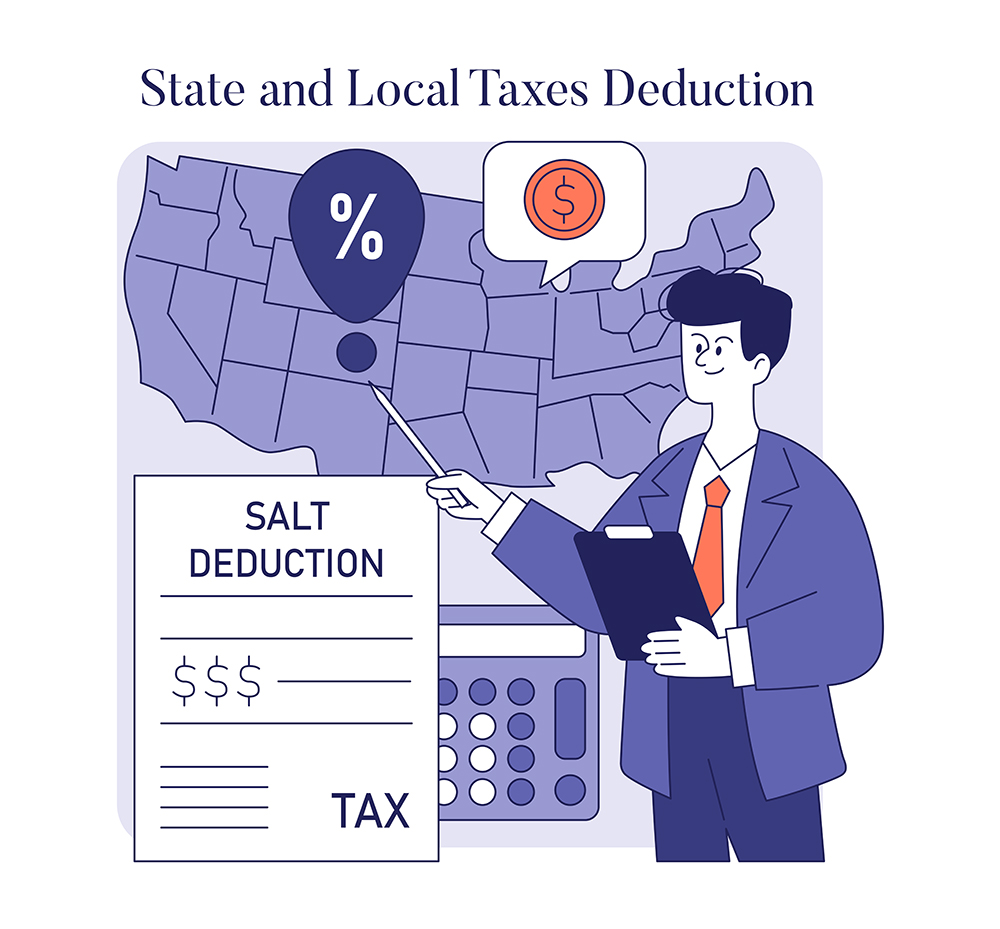
The SALT deduction allows taxpayers who itemize deductions to subtract state and local taxes (SALT) from their federal taxable income. This includes property taxes, state income taxes (or sales taxes if you elect that option), and certain other local taxes.

Under current law (OBBBA), the deduction is capped at $40,400 for 2026 (up from the previous $10,000 limit). It benefits only those whose total itemized deductions exceed the standard deduction. The higher cap is temporary through 2029 and phases down for high-income earners.

SALT can provide significant tax savings for homeowners and residents in high-tax states, but its value depends on your overall tax situation. Consult your tax professional to discuss in more detail.

Life Insurance as a Gift

During this season of giving, you may want to donate more to your favorite charity but lack the funds to do so. Life insurance offers an affordable way to boost your charitable giving.

TAX BENEFITS

There are several ways to give life insurance charitably, some of which may offer tax advantages now or in the future. Talk with your accountant to understand how you can support a charity while gaining potential tax benefits.

CHARITABLE CHOICES

One option is naming a charity as your policy’s beneficiary. This removes the death benefit from your taxable estate while still allowing you to change beneficiaries later if your circumstances change.

Another option is a charitable rider, if your insurer offers one. This rider directs a set percentage of your death benefit to a designated charity, while the remainder goes to your primary beneficiaries. For example, a $500,000 policy with a 10% charitable rider would give $50,000 to the charity, with the rest going to your loved ones.

Ask your advisor which option fits best for your situation.

Understanding Long-Term Capital Gains Rates

In 2026, a married couple filing jointly has $80,000 in taxable ordinary income (after deductions) and $30,000 in qualified dividends and long-term capital gains, for a total of $110,000. The 0% capital gains rate cutoff is $98,900. $18,900 ($98,900-$80,000) of the gain is taxed at 0%. The remaining $11,100 of gains is taxed at 15%.

October 2026 Client Profile

Shawn’s business is touristdependent and earns most of its revenue in the warmer months. He has always filed his tax return on a calendar-year basis but would like to switch to a fiscal year ending in October. What does he need to do?

First, Shawn should confirm his eligibility. The IRS states that if he files his first return using the calendar tax year and later becomes a sole proprietor, a partner in a partnership, or a shareholder in an S corporation, he must continue to use the calendar year unless he obtains IRS approval to change it or meets one of the exceptions listed in the IRS’s Form 1128 instructions.

Shawn may qualify for automatic IRS approval to change his tax year. Your tax professional can help determine whether changing the tax year is the right decision.

Client Profile is based on a hypothetical situation. The solutions discussed may or may not be appropriate for you.

Tax-Loss Harvesting

If investments you sold in 2026 lost money, you may find some solace in the IRS tax code. You can deduct certain losses from your taxable income — a practice known as tax-loss harvesting — if you understand the rules. Here are the basics:

THE RULES

For starters, the IRS has separate tax rates for long-term investments — those that you have held for more than a year. The capital gains tax rate on net realized long-term investment gains, or capital gains, is 15% for most people.

You realize losses and gains only on investments you sell, not on those you still hold. Investments held for a year or less trigger ordinary income tax rates, which are typically higher. The IRS taxes some or all net capital gains at 0% if your income is low enough. You’ll pay 20% on net capital gains if your taxable ordinary income exceeds $545,501 if filing as a single, $613,701 if filing jointly, $579,601 if filing as head of household, and $306,851 if married and filing separately.

THE CALCULATION

To calculate net losses, subtract the amount you realized from selling your investment from the original investment amount, then deduct any sales charges. If your realized capital losses exceed your realized capital gains, deduct up to $3,000 per year for individuals and married couples filing jointly, or up to $1,500 if married and filing separately. You may carry forward any losses exceeding this annual cap to future years.

LONG-TERM VIEW

Don’t sell investments solely for tax reasons. Hold those that lost money last year if they still have long-term prospects, and sell winners that don’t fit your investment strategy.

Ace Enrollment as an Employer

As open enrollment approaches, clear communication helps employees make informed decisions and increases engagement with your benefits package.

Highlight the Value

Regularly remind employees that benefits often make up 20–40% of total compensation. Sharing this information helps attract and retain top talent by demonstrating the full value of their compensation package.

Use Multiple Channels

Use mobile apps and digital tools for younger workers, and print materials and in-person sessions for others. Consistent, multi-channel outreach ensures broader reach during the critical period.

Keep It Simple and Supportive

Provide easy-to-access resources — hotlines, HR support, or FAQs. Effective communication during open enrollment turns a routine process into a powerful retention tool.

Fall Into Smart Benefits: Enrollment Tips

As summer ends and fall begins, employers nationwide are preparing to offer their annual open enrollment for employee benefits. Whether you’re new to selecting benefits or a seasoned pro, it’s essential to research thoroughly before making your choices.

REVIEW YOUR OPTIONS

Health and other benefit options can change from year to year, even when providers haven’t. Health insurance plans regularly adjust premiums, deductibles and other out-of-pocket costs, and employers may pass those increases on to employees. Plans add and remove network health providers and may also adjust peripheral benefits such as chiropractic care and acupuncture.

You’ll also want to review any health savings plans offered, including the Health Savings Account (HSA) if you have a high-deductible health plan. HSA contributions are made pretax, and potential earnings and qualified withdrawals are tax-free. In 2027, contribution limits will increase to $4,500 for self-only coverage and $9,000 for family coverage.

ADDITIONAL BENEFITS

While health insurance is the primary “want” for most employees, other benefits may play an important role in your financial and risk planning. Employersponsored life insurance — typically term — can provide a solid foundation of coverage to help protect loved ones. Because it is group life insurance, it typically won’t require underwriting — an important consideration for employees with preexisting conditions.

Disability income (DI) insurance may also be important coverage for younger employees, who are much more likely to become disabled than to die at that age. This insurance protects what is many employees’ largest asset — their ability to earn a living.

Life insurance, DI and other benefits may also be tax-advantaged, reducing taxable income and, ultimately, taxes. These are a few of what can be many benefit offerings.

Discuss your choices with your financial and tax professionals.
October 2026 Client Line Newsletter

Fall Into Smart Benefits: Enrollment Tips – whether you’re new to selecting benefits or a seasoned pro, it’s essential to research thoroughly before making your choices.

Ace Enrollment as an Employer – clear communication helps employees make informed decisions and increases engagement with your benefits package.

Tax-Loss Harvesting – if investments you sold in 2026 lost money, you may find some solace in the IRS tax code.

October 2026 Client Profile

Understanding Long-Term Capital Gains Rates

Life Insurance as a Gift – life insurance offers an affordable way to boost your charitable giving.

October 2026 Question and Answer

Key Deadlines to Consider – by doing a little year-end planning now, you can optimize your unique financial situation.

Higher SALT Cap may Change Your Filing Strategy – new limits for 2026 could open the door to bigger tax savings.